Medical Invoice Factoring: A Solution for Slow Insurance Payments
Insurance reimbursements can take weeks or months, but payroll and rent are due now. Medical practices factor insurance receivables to…
Healthcare providers wait on insurers while their own bills keep coming due. Medical invoice factoring advances cash against those claims. Learn how it differs from a loan and how to choose a factor that knows healthcare billing.
Healthcare providers have a primary mission: to deliver excellent patient care. However, financial challenges in the healthcare industry often create significant obstacles. Delayed payments from insurance companies, complicated billing processes, and ongoing operational costs can lead to serious cash flow issues. This financial pressure can distract from patient outcomes and limit a practice’s growth potential.
Medical invoice factoring is a financial solution designed to tackle these specific challenges. Turning unpaid insurance claims and patient invoices into immediate cash provides the liquidity needed to maintain economic stability. This article explores how medical invoice factoring works, its main benefits, and how it helps healthcare providers streamline their cash flow so they can focus on what truly matters: their patients.
Medical invoice factoring is a financial transaction where a healthcare provider sells its outstanding accounts receivable (unpaid invoices) to a specialized third party called a factoring company. In exchange, the provider receives an immediate cash advance, typically a large percentage of the total invoice value. This process effectively converts slow-paying insurance claims into accessible working capital.
Instead of waiting weeks or months for payments from insurance companies, Medicare, or Medicaid, providers can receive an advance the same day they submit claims, once the account is set up. The factoring company takes over the task of collecting payment from the third-party payer. Once the invoice is fully paid, the factoring company sends the remaining balance to the provider, minus a pre-agreed fee for the service.
Medical factoring is not a type of debt, unlike a traditional bank loan. You’re not borrowing money; you’re selling an asset—your accounts receivable. This difference is essential. Since it doesn’t increase your debt load, it won’t affect your ability to secure other financing for long-term investments, like new equipment or facility expansion.
Traditional loans often require a lengthy approval process, a detailed credit history, and significant collateral. Medical factoring, in contrast, is faster and easier to access. Approval is mainly based on the creditworthiness of your payers (the insurance companies), rather than the financial history of your practice. This makes it an excellent option for newer practices or those that might not qualify for traditional bank loans.
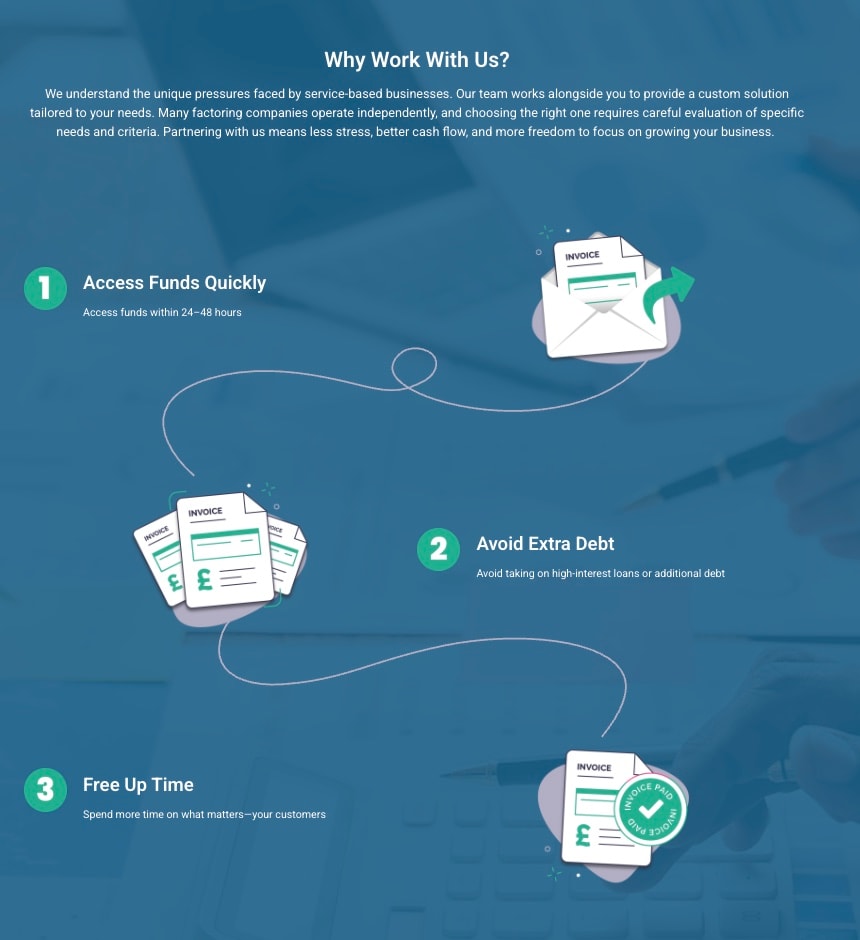
The medical invoice factoring process is designed for simplicity and speed.
1. Submit Invoices: The healthcare provider submits unpaid invoices from reliable third-party payers to the factoring company.
2. Receive Cash Advance: The factoring company checks the invoices and advances a significant portion of their value, typically 80% to 90%, to the provider the same day the invoices are submitted.
3. Collection Process: The factoring company oversees the collection process, following up with the insurance companies or government payers to ensure timely payment.
4. Receive Remaining Balance: Once the payer settles the invoice, the factoring company sends the remaining balance to the healthcare provider, after deducting its factoring fee.
Most medical factoring operates on a “recourse” basis. This means that if an insurance company challenges a claim or refuses to pay for reasons other than their own financial problems (like a coding error), the healthcare provider must buy back that invoice from the factoring company.
One of the biggest financial hurdles in healthcare is the long wait to receive payments. Insurance companies, government programs like Medicare and Medicaid, and other third-party payers often have lengthy and unpredictable payment cycles. It’s common for a provider to wait 30, 60, or even over 90 days to get reimbursed for services provided.
These slow payments create significant cash flow gaps and considerable financial stress. While revenue may look strong on paper, a lack of liquid cash can hinder the effective running of the practice. This ongoing uncertainty disrupts financial planning and can put the entire operation at risk.
The complexity of healthcare billing adds another layer of difficulty. Managing insurance claims requires navigating a maze of coding needs, pre-authorizations, and payer-specific rules. A single coding or documentation error can lead to a denied claim, forcing the provider to restart the extended submission and appeals process.
This administrative workload is time-consuming and expensive. Staff must devote numerous hours to filing claims, following up on payments, and managing denials. This takes valuable resources away from patient-focused tasks and contributes to operational inefficiencies that hurt cash flow.
While waiting for payments, healthcare providers still need to cover regular operational expenses. These costs are consistent and often significant, including staff payroll, rent or mortgage for the facility, medical supplies, insurance, and technology upgrades.
When cash flow is irregular, meeting these obligations becomes difficult. Providers may have to delay payments to suppliers, postpone needed equipment upgrades, or even struggle to make payroll. This financial stress not only affects the business but can also impact the quality of patient care.
The main advantage of medical factoring is the immediate cash infusion it provides. This quick access to funds allows healthcare practices to cover operational costs without delay. Whether it’s making payroll, buying necessary medical supplies, or paying rent, factoring ensures you have the working capital you need, when you need it. This fixes the cash flow gaps caused by slow-paying insurance claims.
Converting unpredictable receivables into a steady cash flow reduces financial stress significantly. This stability allows for better financial planning and budgeting. Healthcare providers can manage their finances confidently, knowing they have a reliable funding source. Effective accounts receivable management becomes a natural result of the factoring relationship.
Many medical factoring companies take on the billing and collection process for the provider. This service is a significant advantage because it frees up administrative staff from the time-consuming task of collecting payments from insurance companies. By outsourcing collections, healthcare providers can reduce administrative costs and enable their team to focus on more critical activities, such as patient care and practice growth.
Since factoring is the sale of an asset, it does not increase debt on your practice’s balance sheet. This is a significant benefit, especially for small or growing healthcare organizations that want to maintain a clean financial profile. You can access the funds you need to operate without the long-term obligations and interest payments tied to a traditional loan.
With more effortless cash flow and less administrative work, healthcare providers can return their focus to their core mission: delivering high-quality patient care. The financial flexibility from factoring can also support business growth. Providers can use the consistent working capital to invest in new medical technology, expand services, open new locations, or run marketing campaigns to attract new patients.
Choosing the right factoring partner is essential for a successful relationship. Look for a company with transparent pricing and straightforward terms. Be cautious of hidden fees or complicated contracts. Evaluate potential partners based on their advance rates, factoring fees, and their customer service quality. A trustworthy partner will be open about all costs and work with you to find a solution that fits your practice’s needs.
The healthcare industry has unique billing processes and regulations, such as HIPAA. It’s crucial to pick a factoring provider that specializes in medical receivables. An experienced medical factoring company will understand the complexities of working with insurance companies, Medicare, and Medicaid. This expertise ensures they can manage your claims efficiently and in compliance, offering a tailored solution for your specific cash flow needs.
Your factoring partner will be an extension of your business, interacting with your payers. You need a dependable company that offers professional customer support. A good partner will be available to answer your questions and help you deal with any financial challenges that come up. Check references and read reviews to assess a company’s reputation for reliability and service.
Carefully review any factoring agreement before signing. Watch for hidden fees, like application fees, processing fees, or cancellation penalties. Look for a factoring company that provides flexible terms that match your business goals. Avoid being locked into long-term contracts with high minimum volume requirements if your cash flow needs change.
One direct application of medical factoring is to use it as a strategy to handle delayed insurance payments. By factoring your claims, you can smooth out the fluctuations in your cash flow caused by slow payers. This proactive approach ensures you always have the working capital needed to operate your practice without interruptions.
Growth is exciting, but it often leads to increased expenses. Expanding services, adding new staff, or opening a new facility all require substantial upfront investment. Factoring offers the financial flexibility needed to navigate these growth phases successfully. It allows you to fund your expansion without taking on debt, ensuring you maintain positive cash flow even as operational costs rise.
Medical factoring works best when it’s part of a larger financial plan. It can complement other financial tools, like a traditional line of credit for long-term investments. By combining different financing options, you can develop a strong and flexible strategy that addresses both your short-term operational needs and your long-term growth goals.
A small, independent physical therapy clinic was struggling with inconsistent cash flow due to slow reimbursements from private insurance and Medicare. The practice was profitable, but the 60-day payment cycle made it tough to cover monthly rent and payroll. By working with a medical factoring company, the clinic was able to factor its invoices and receive an 80% advance within two days. This immediate cash boost stabilized their finances, allowing them to meet all their operational costs on time and even invest in new therapy equipment.
A mid-sized home healthcare agency encountered significant administrative challenges in managing claims for hundreds of patients covered by various insurance plans. Their billing department was overwhelmed, resulting in errors and further payment delays. The agency turned to a medical factoring company offering full-service billing and collections support. The factoring partner managed the entire accounts receivable process, improving collection times and reducing claim denials. This not only enhanced the agency’s cash flow but also allowed its staff to focus on coordinating patient care.
The experiences of these providers highlight an essential lesson: medical factoring is more than just a quick cash source. When used strategically, it is a complete cash flow management tool. The most successful users are those who select a factoring partner with deep industry knowledge and leverage the relationship to stabilize their finances and simplify their administrative processes.
You should consider medical factoring if your practice consistently faces cash flow shortages due to slow-paying insurance claims. It is an ideal solution if you need immediate working capital to cover operational expenses or fund growth, but want to avoid taking on traditional debt. If the administrative burden of billing and collections is diverting resources from patient care, factoring can also provide significant relief.
Medical invoice factoring provides the financial stability needed to operate a healthcare practice effectively. Ensuring immediate and predictable cash flow reduces financial stress and allows for better planning. It also supports growth by providing the capital to invest in your practice, expand your services, and ultimately enhance the quality of patient care you deliver.
If medical factoring could benefit your practice, the next step is to conduct thorough research. Identify reputable factoring companies that specialize in the healthcare industry. Prepare a summary of your accounts receivable and cash flow needs, and reach out to a few potential partners to discuss your situation and request a proposal.
Medical invoice factoring offers a practical and effective solution to the persistent cash flow challenges faced by healthcare providers. By turning unpaid invoices into immediate working capital, it simplifies financial management, reduces administrative burdens, and empowers providers to focus on their primary mission of patient care.
Choosing the right factoring partner—one with industry expertise, transparent practices, and a commitment to service—is key to unlocking the full benefits of this financial tool. For healthcare businesses seeking greater economic stability and long-term growth, medical factoring presents a viable and valuable solution worth exploring.
Common Questions
Most businesses receive 80–90% of the invoice value up front. Freight carriers receive a full advance, which is standard in freight factoring, and we make exceptions to the range case by case. When your customer pays, we release the remaining balance to you, minus our fee.
Setting up your account typically takes 24–48 hours from signup. After that, we fund invoices the same day you submit them.
Sigma factors with recourse, so an invoice your customer never pays comes back to you. You can add credit insurance, which pays when an insured customer fails to pay, under the policy's terms. We don't offer non-recourse factoring. It costs more and covers only a customer's bankruptcy or insolvency, so late payment and non-payment stay with you anyway. Compare the options.
Yes. A Notice of Assignment tells your customer to send payment to Sigma, so how we handle collections and communication matters. The staffing and service business pages explain how that works in practice.
Factoring is the sale of invoices you've already issued, so the funding grows with your sales. A line of credit is a loan with its own underwriting and covenants. Read factoring vs. a line of credit for a side-by-side comparison.
Tell us about your business and the invoices you want funded. Within 48 hours you get a proposal with your advance rate, fee and terms, and you don't have to sign it.
Your advance
Get Your Proposal