How Service-Based Businesses Can Use Factoring to Grow
Service businesses often finish the work weeks or months before the client pays. Factoring turns those invoices into cash for…
Service businesses often wait 30 to 90 days to be paid for finished work. Here's what factoring gives them during that wait and how to tell whether your business qualifies.
Service-based businesses face a unique challenge that can make or break them: the gap between completing work and getting paid. You’ve delivered excellent service, sent the invoice, and now you wait. Sometimes for 30, 60, or 90 days.
This cash flow gap creates a domino effect. You can’t pay your team on time. New opportunities slip away because you don’t have the working capital to take them on. Growth stalls while you chase down payments from clients who seem to have forgotten your invoice exists.
For many service-based businesses, this cycle feels endless. But there’s a financial tool that can break this pattern and turn your cash flow challenges into competitive advantages: invoice factoring.
Invoice factoring gives you immediate access to cash by converting your outstanding invoices into working capital. Instead of waiting months for payment, you can get 80% to 90% of your invoice value the same day you submit it. This isn’t just about solving cash flow problems, it’s about creating the financial foundation for sustainable growth.
The benefits go far beyond immediate cash access. Invoice factoring provides flexibility without adding debt to your balance sheet, reduces the administrative burden of collections, and gives you the financial stability to pursue bigger contracts and growth opportunities with confidence.
Invoice factoring is for businesses across many industries, but some types of companies find it more valuable. Service-based businesses often benefit most because they have longer payment cycles and need consistent cash flow to cover operational expenses.
1. Immediate Cash Flow
The most apparent benefit of invoice factoring is the immediate access to working capital. Instead of waiting 30, 60, or 90 days for client payments, you can get most of your invoice value the same day you submit an invoice.
This immediate cash access changes how you manage daily operations. You can:
The speed of cash access also allows you to respond quickly to new opportunities. When a potential client offers a big project that requires upfront investment, you can accept with confidence knowing you have the working capital to deliver outstanding results.
Invoice factoring creates predictable cash flow patterns that make financial planning more manageable. Instead of experiencing feast-or-famine cycles based on when clients pay, you can forecast your cash position more accurately.
This financial stability extends to your ability to cover essential operational expenses. Payroll becomes predictable, rent payments are consistent, and you can plan for growth without worrying about cash flow interruptions.
Invoice factoring doesn’t just provide cash flow—it also reduces the time and effort spent on collections. When you work with a factoring company, they take on the responsibility of collecting payments from your clients.
This means your team can focus on core business activities like delivering excellent service and growing your client base, rather than chasing down overdue invoices. The factoring company’s expertise in collections often results in faster payments and fewer disputes, further improving your cash flow.
Unlike traditional loans, invoice factoring doesn’t add debt to your balance sheet. Instead, it’s a transaction where you sell your invoices at a discount in exchange for immediate cash.
This flexibility is particularly valuable for businesses that may not qualify for traditional financing due to limited credit history or lack of collateral. Approval for factoring is based primarily on your clients’ creditworthiness, not your company’s financial standing.
Additionally, factoring is scalable. As your business grows and your invoice volume increases, the amount of working capital available to you grows as well. This makes factoring an ideal solution for businesses experiencing rapid growth or seasonal fluctuations.
The process of invoice factoring is straightforward and can be set up quickly. Here’s how it works:
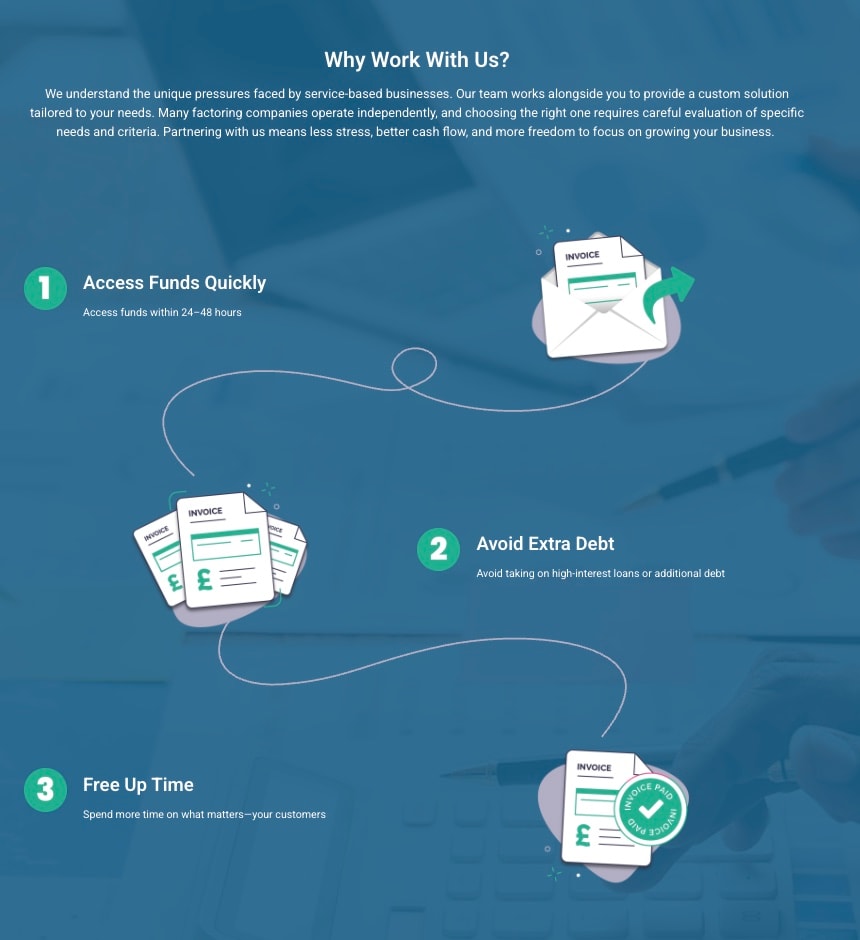
This simple process allows you to turn unpaid invoices into immediate working capital without waiting for clients to pay.
Invoice factoring is a powerful tool, but it’s not the right fit for every business. Here are some factors to consider when deciding if factoring is the right solution for you:
Invoice factoring is more than just a cash flow solution, it’s a strategic tool that can help service-based businesses overcome financial challenges, reduce administrative burdens, and unlock growth opportunities.
By converting unpaid invoices into immediate working capital, factoring allows you to focus on what you do best: delivering exceptional service to your clients. Whether you’re a small business looking to stabilize cash flow or a growing company ready to take on bigger projects, factoring can provide the financial foundation you need to succeed.
If your business is struggling with cash flow gaps or delayed client payments, it might be time to explore how invoice factoring can transform your operations and set you on the path to sustainable growth.
Common Questions
Most businesses receive 80–90% of the invoice value up front. Freight carriers receive a full advance, which is standard in freight factoring, and we make exceptions to the range case by case. When your customer pays, we release the remaining balance to you, minus our fee.
Setting up your account typically takes 24–48 hours from signup. After that, we fund invoices the same day you submit them.
Sigma factors with recourse, so an invoice your customer never pays comes back to you. You can add credit insurance, which pays when an insured customer fails to pay, under the policy's terms. We don't offer non-recourse factoring. It costs more and covers only a customer's bankruptcy or insolvency, so late payment and non-payment stay with you anyway. Compare the options.
Yes. A Notice of Assignment tells your customer to send payment to Sigma, so how we handle collections and communication matters. The staffing and service business pages explain how that works in practice.
Factoring is the sale of invoices you've already issued, so the funding grows with your sales. A line of credit is a loan with its own underwriting and covenants. Read factoring vs. a line of credit for a side-by-side comparison.
Tell us about your business and the invoices you want funded. Within 48 hours you get a proposal with your advance rate, fee and terms, and you don't have to sign it.
Your advance
Get Your Proposal